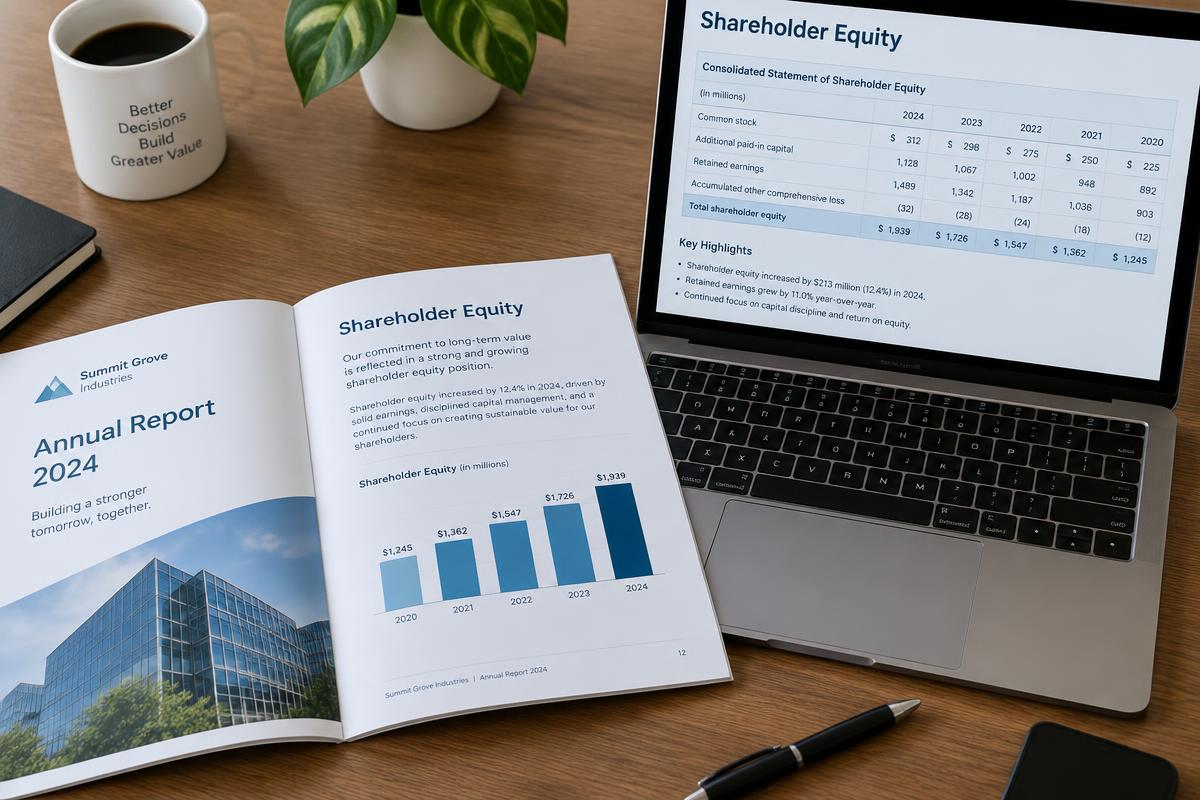
Statement of changes in equity
This statement shows all changes to equity for the period, including changes in retained earnings, other comprehensive income, common stock (par or stated value), and additional paid-in capital.
| Line | Detail | Total |
|---|---|---|
| Retained earnings, January 1 | $700,000 | |
| Net income | 600,000 | |
| Dividends declared | (200,000) | |
| Retained earnings, December 31 | $1,100,000 | |
| Accumulated OCI, January 1 | $300,000 | |
| OCI | 200,000 | |
| Accumulated OCI, December 31 | $500,000 | |
| Common stock, January 1 | $750,000 | |
| Shares issued | 250,000 | |
| Common stock, December 31 | $1,000,000 | |
| Additional paid-in capital, January 1 | $1,000,000 | |
| Shares issued | 340,000 | |
| Additional paid-in capital, December 31 | $1,340,000 | |
| Total equity | $3,940,000 |
Statement of retained earnings
One of the basic financial statements, it shows the increases and decreases to retained earnings for the same period as the statement of income: the beginning balance, any prior-period adjustments net of tax, net income or loss, dividends paid or declared, and the ending balance.
| Line | Amount |
|---|---|
| Beginning retained earnings | $700,000 |
| Prior period adjustment — overstatement of depreciation expense | 100,000 |
| Beginning retained earnings restated | $800,000 |
| Net income | 600,000 |
| Cash dividends paid | (200,000) |
| Ending retained earnings | $1,200,000 |
Comprehensive income
Comprehensive income is the change in equity (net assets) of a business enterprise during a period from transactions and other events and circumstances from non-owner sources. It includes all changes in equity during a period except those resulting from investments by owners and distributions to owners, and should assist investors, creditors, and others in assessing an entity's activities and future cash flows.
- Includes all components of net income and other comprehensive income (OCI).
- OCI includes unrealized gains and losses on available-for-sale securities.
- OCI includes gains and losses on derivatives that are cash flow hedges.
- OCI includes certain amounts associated with the funded status of post-retirement defined benefit plans, and certain foreign currency items.
- Each component of OCI must be presented net of tax.
- The statement of comprehensive income can be presented as one continuous statement with two sections, or as separate but consecutive statements: the statement of income with a total for net income and its components, and the statement of other comprehensive income with totals for OCI and for comprehensive income.
Notes to the financial statements
- Financial statement notes are an integral part of financial statements.
- FASB requires disclosure of the accounting policies adopted by an entity, as this is essential information for financial statement users.
- Notes contain information critical to properly understanding and analyzing a company's financial statements.
- Notes disclosing accounting policies identify the accounting principles followed, the methods of applying them that materially affect financial position, cash flows, or results of operations, and important judgments about revenue recognition and the allocation of asset costs to current and future periods.
- Examples of note disclosures: depreciation methods used, amortization of intangibles, inventory pricing methods, and the method used to recognize profit on long-term construction-type contracts.
Corporate annual reports and SEC reporting
The SEC was created by the Securities Exchange Act of 1934 to regulate securities markets and to require full disclosure, in part through the issuance of financial statements. Publicly traded corporations must file annual and quarterly reports with the SEC, plus periodic reports that include financial statements.
- Form 10-K
- The annual report to the SEC. Includes standard financial statements and other important supplemental information, must be filed within 60 days of the last day of the fiscal year for large corporations, and is certified by an independent accountant (CPA firm) and signed by the principal executive, financial, and accounting officers and a majority of the board of directors.
- Form 10-Q
- The quarterly report sent to the SEC. Includes interim financial statements, reviewed but unaudited by an independent accountant, similar to the annual financial statements. Discloses changes during the quarter for events such as lawsuits and increases, decreases, or changes in securities issued by the corporation.
Guide: Financial Statements
NEXT · PART SEVEN: Nonprofit, Governmental and Personal Statements
Continue the guide